

Settlemate analysis by Appwee
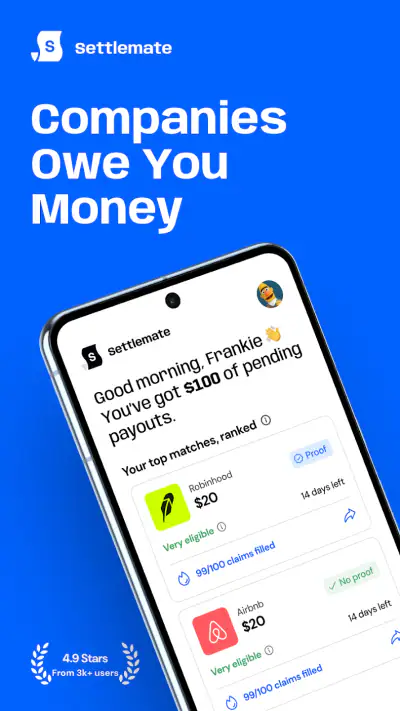
Settlemate is a finance app built around a simple but unusually practical idea: helping people find money that companies may owe them. That focus immediately separates it from budgeting tools, banking dashboards, and expense trackers. Instead of asking me to monitor every purchase or plan a monthly limit, it points my attention toward a different financial task: checking whether an old company interaction may have left a payment, refund, settlement, or other compensation available.
That makes the app interesting for anyone who has used many services over the years and rarely remembers what happened after a billing dispute, product issue, subscription problem, or consumer complaint. I found the concept more useful than the short store wording suggests because it changes the question from “How do I save more?” to “Is there money I have already earned the right to claim?”
The strongest reason to try Settlemate is its narrow purpose. A general finance app can show balances and spending patterns, but it usually does not encourage me to revisit past relationships with companies. Settlemate is aimed at that overlooked part of personal finance. It is free to install, rated for Everyone, and developed by Settlemate. Its current version is 4.5.1, and it runs on Android 8.0 or later.
Turning forgotten company interactions into a financial check
The capability that sets it apart
The central capability is not ordinary money management. Settlemate is designed to help users identify potential money owed by companies. That distinction matters because the value is often hidden in the past rather than visible in a current account. A budgeting app may tell me that I spent too much on delivery, streaming, travel, or retail. This app encourages me to examine whether any of those transactions, disputes, or service experiences connect to a payment opportunity.
In practice, I would treat it as a financial search and follow-up tool rather than a daily dashboard. I would open it when I remember a company that caused a billing problem, when I hear about a consumer settlement, or when I want to review older accounts and purchases. That makes the app more occasional than a banking app, but occasional does not mean unimportant. A single useful discovery can justify returning to a tool that I do not need every morning.
The idea also suits people who are not naturally organized with receipts and emails. Many of us delete confirmation messages, change email addresses, forget the exact name of a service, or assume that small amounts are not worth pursuing. Settlemate’s purpose is valuable precisely because it brings attention back to those loose ends. It gives a person a reason to investigate instead of relying on memory alone.
What using it feels like
I would approach the app with realistic expectations. It is not a magic balance finder, and it should not be treated as guaranteed income. A possible match still needs to make sense for my situation, and any claim or request may require accurate personal details or supporting information. The app can make the search easier to start, but it cannot turn an ineligible user into an eligible one.
That is an important practical distinction. The best result is not simply seeing a possible opportunity; it is understanding why it might apply, what action is required, and whether the effort is worthwhile. I would read each item carefully, check the relevant company or service, and avoid submitting anything based only on a familiar-sounding name. Similar brands, old promotions, and overlapping services can make rushed decisions risky.
Settlemate therefore works best when I use it as a prompt for careful verification. I would keep a small record of the companies I have used, the email addresses connected to them, and any dates or transaction details I can still locate. Even a basic note in my phone can make the process more efficient. The app’s main benefit is helping me notice opportunities; my own records help determine whether those opportunities are genuinely relevant.
A realistic everyday scenario
Imagine that I have used several delivery platforms, online retailers, subscription services, and mobile providers over the years. One service charged me after I thought I had canceled, another delivered a damaged item, and a third sent a confusing notice about a billing adjustment. At the time, I may have contacted support once and then moved on. Months later, I would probably remember the frustration but not the exact account details.
This is where I would open Settlemate. I could use the app as a checklist for companies I recognize, then search my inbox for old receipts, cancellation messages, or support conversations. If something appears relevant, I would compare the app’s information with my own records before taking the next step. That workflow is more sensible than opening the app randomly and expecting it to produce a result without any context.
The less obvious advantage is that this process can reveal how scattered my consumer history has become. I may discover that an old account uses a different email address, that a purchase was made through a family member, or that the company name on my bank statement differs from the brand name I remember. Those details do not make the app itself more powerful, but they show why a focused reminder tool can be useful: it gets me looking in the places where the evidence actually lives.
How I would decide whether to act
I would use a three-step habit. First, I would identify the company or service and confirm that I personally interacted with it. Second, I would look for matching dates, account information, receipts, or correspondence. Third, I would read the requirements before sharing information or spending time on a submission.
This approach prevents a common mistake: treating every possible result as free money. Some opportunities may involve eligibility rules, deadlines, documentation, or a payment that is too small to justify a lengthy process. Others may be easy to pursue but still require patience. Settlemate is most helpful when it reduces the chance that I overlook something, not when it encourages me to click through every result without judgment.
I would also avoid entering information simply because an item looks promising. A finance-related app deserves the same caution as any service handling personal details. I would check the wording, understand why information is requested, and stop if the process feels unclear. The app’s purpose is useful, but good judgment remains part of the workflow.
Where it has an advantage over familiar alternatives
The usual alternatives solve different problems. A banking app is better for checking current balances and transactions. A budgeting app is better for categorizing spending and setting limits. A spreadsheet is better for maintaining a personal record of claims, receipts, and deadlines. A search engine can find public information, but it leaves me to judge which results are relevant and how to organize them.
Settlemate sits between discovery and personal follow-up. Its advantage is focus: it is not asking me to build a complete financial system before I can investigate money that may be owed. For someone who already has a budget and wants a separate way to review company-related opportunities, that specialization is convenient.
The trade-off is that it is not a replacement for those other tools. It will not give me the same control as a spreadsheet for tracking every document, and it is not the right choice if my main goal is reducing monthly spending. I would pair it with my bank and email rather than expect it to replace them. That combination is more useful than choosing one app for every financial task.
Important friction before downloading
Settlemate has a free price, which makes trying its core idea relatively easy. At the same time, it includes in-app purchases ranging from $1.99 to $64.99 per item. I would pay close attention to any paid step, upgrade, or optional service before confirming it. Free installation does not automatically mean that every part of the experience is free.
That pricing structure is not necessarily a problem, but it changes how I would evaluate the app. If I only want to browse and understand the concept, I would begin without committing to a purchase. If a paid option appears, I would compare its cost with the likely value of the opportunity and read exactly what it provides. A small possible payment should not lead me into a much larger expense.
Another limitation is the occasional nature of the task. People who want constant financial feedback may find the app less engaging than a budget tracker. Its usefulness depends on whether there are relevant company interactions in my history and whether I am willing to verify them. Someone with very few online purchases or no interest in checking old accounts may gain little from it.
I would also avoid using it as a substitute for direct communication when a normal refund or billing dispute is still open. If a company has already acknowledged an error, contacting that company may be faster than treating the matter as a broader opportunity. Settlemate is more valuable for forgotten, unclear, or easily missed possibilities than for a straightforward support ticket I can resolve today.
Who gets the most value
The best audience is people with a long trail of consumer activity: frequent online shoppers, subscription users, travelers, mobile customers, and anyone who has dealt with several large service providers. It is especially suitable for users who keep discovering old emails after a problem has already faded from memory. The app gives those loose ends a place to start.
It may also help households where one person handles most purchases but does not have perfect records. In that situation, I would involve the person who made the transaction before submitting anything. A shared review can prevent confusion about whose account was used, which email received the receipt, or whether a family member has already taken action.
People who are comfortable with careful paperwork may find the app useful as a discovery layer, then move the details into a spreadsheet or notes app. The spreadsheet can hold the company name, the reason it may apply, the evidence found, the action taken, and any follow-up date. This is one of the most practical ways to get more value from a focused app without asking it to become a complete record system.
On the other hand, I would skip Settlemate if I mainly want investment tracking, bill reminders, debt payoff planning, or automatic expense categorization. Those needs call for different finance tools. I would also skip it if I am unwilling to read eligibility conditions or verify old transactions. The app can point me toward a possibility, but it cannot remove the responsibility to check the details.
My overall impression after weighing the idea
Settlemate is appealing because it focuses on a part of personal finance that most people ignore. The concept is easy to understand, yet the real usefulness depends on how thoughtfully I use it. I would not open it every day, but I could see myself returning whenever I review old subscriptions, clean up an inbox, or remember a company dispute that never felt fully resolved.
The app has already reached over 500,000 installs, with an average rating of 4.3 from around 38,000 ratings and around 2,200 written reviews. Those figures suggest that the idea has found an audience, although they do not remove the need to judge each opportunity carefully. For me, the strongest sign of quality is not the popularity alone but whether the app helps turn vague memories into a clear, responsible next step.
My recommendation is positive for the right user. If you want a focused way to investigate whether companies may owe you money, Settlemate is worth trying, especially because the download is free and the age rating is Everyone. I would use it alongside a bank app, email search, and a simple personal log, while treating paid options and information requests with caution.
In the end, I see it as a specialized financial reminder rather than a complete money manager. That narrow role is both its strength and its boundary. If you have a history of forgotten subscriptions, disputed purchases, or unresolved company interactions, Settlemate can help you look in the right direction; if you need everyday budgeting, another app will serve you better.
Gallery
Settlemate Pros and Cons
- Simple interface makes tracking shared expenses easy.
- Supports clear settlement calculations between multiple people.
- Useful for trips
- roommates
- and recurring group expenses.
- Reduces confusion by keeping payment details in one place.
- Helps users see who owes money before settling up.
- Requires everyone to enter expenses accurately for reliable results.
- May feel unnecessary for very small or one-time payments.
- Limited value if your group prefers cash or informal tracking.
- Users may need to remind others to update shared expenses.
- Privacy concerns may arise when entering financial information.
Settlemate Frequently Asked Questions
What is Settlemate and what can I use it for?
Settlemate is designed to help users organize and manage shared expenses, making it useful for trips, roommates, group activities, or everyday bills. Before downloading, check which features are available in your region and whether the app supports your preferred currency, payment method, and expense-sharing style. Its usefulness depends on how consistently everyone in the group records and reviews transactions.
How does Settlemate split expenses between users?
Settlemate generally allows users to add shared costs, select the people involved, and divide the amount according to equal or customized shares. This can be helpful when participants contribute different amounts or do not share every expense. Review each entry carefully before confirming it, especially when taxes, tips, discounts, partial payments, or multiple currencies are involved, since incorrect details can affect the final balance.
Does Settlemate require an account or an internet connection?
The exact requirements may vary depending on the current version of Settlemate and the platform you use. Some features may require account creation, invitations, synchronization, or an active internet connection, while basic information might remain available locally. Check the app’s permissions, sign-in options, and privacy information before registering, particularly if you prefer not to connect financial or personal data to a cloud-based service.
Is Settlemate safe for managing financial information?
Settlemate may handle sensitive details such as names, expense descriptions, balances, and group activity, so users should review its privacy policy and requested permissions before use. It is best to avoid entering unnecessary banking credentials or highly confidential information unless the app clearly explains why it is needed. Use a strong password, keep the application updated, and only share expenses with trusted participants.
Is Settlemate free to download and use?
Settlemate’s pricing can depend on the operating system, region, and version available in the app store. Although the initial download may be free, some functions could be limited by subscriptions, in-app purchases, advertisements, or premium group-management tools. Check the store listing for current pricing and trial conditions before downloading, and confirm whether recurring charges will apply after any promotional period ends.














